Registration Duties in Flanders (3%) vs Brussels (12.5%)
Finding the perfect home in Belgium often leads to a sudden, painful realization: the price you see on Immoweb is just the starting point. I remember the exact moment my partner and I realized that a 12.5% tax in Brussels meant we needed an extra fifty thousand euros just to hand to the government. This guide clears up the massive confusion surrounding registration duties across the different regions.
The Belgian Real Estate Tax Maze
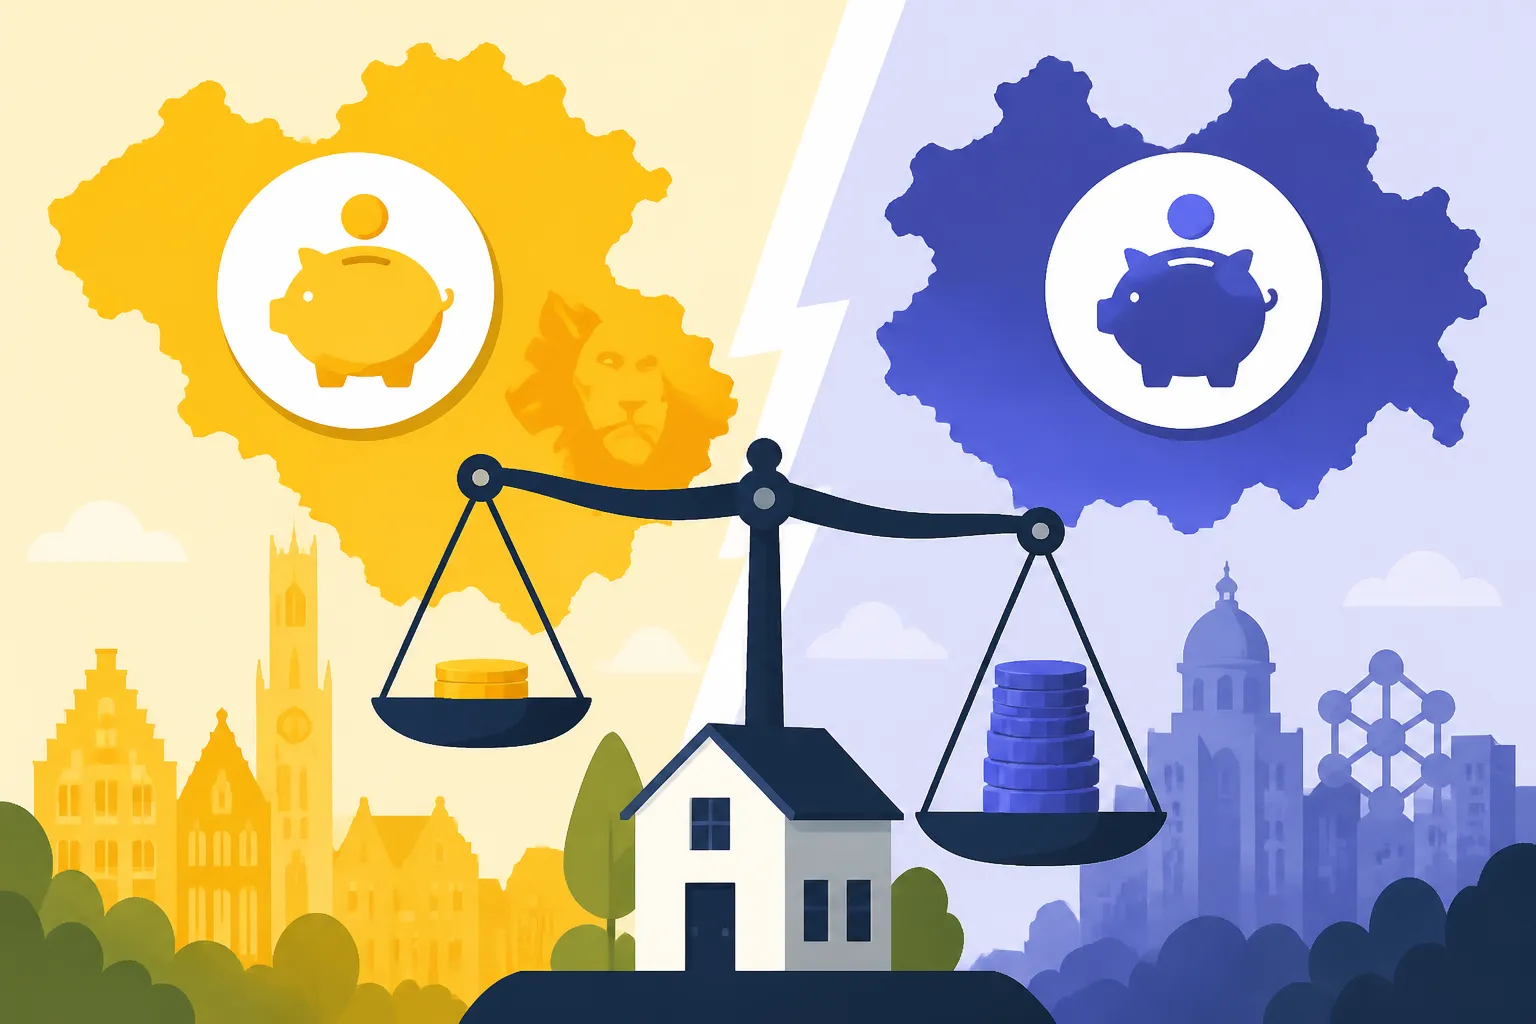
When you buy a property in Belgium, you aren't just paying the seller; you are paying the region for the privilege of registering your ownership. These are known as registration duties, and because Belgium is a federalized country, each region sets its own rules. This leads to one of the most lopsided financial landscapes in Europe. Depending on which side of a street you buy—say, on the border of Flanders and Brussels—you could be looking at a difference of tens of thousands of euros in upfront costs.
For most expats, the initial shock comes during the Buying Property vs Renting in Belgium: Financial 2026 Comparison. While renting is straightforward, buying requires a massive amount of liquid capital. You cannot typically roll these taxes into your mortgage. Banks in 2026 are stricter than ever, usually requiring you to cover all "frais de notaire" (notary fees and taxes) with your own savings. This is where having your house fund in a high-yield environment like Trade Republic can be a lifesaver, allowing your deposit to grow while you navigate the months-long search process.
Why Registration Duties Matter So Much
These duties are the single largest "hidden" cost of moving. Unlike the Cost of Living in Belgium 2026: Budgeting for Cities and Families, which you can adjust by eating out less or taking the train, registration duties are non-negotiable and due at the time of the deed's signature. If you are transferring funds from outside the Eurozone to cover these costs, using a service like Wise is highly recommended to avoid the predatory exchange rates traditional Belgian banks often charge on large five-figure transfers.
Flanders: The Land of the 3 Percent Carrot
Flanders has spent the last few years aggressively lowering its registration duties to encourage people to own the home they live in. As of 2026, the standard rate for your "sole, own residence" is a remarkably low 3%. This is a massive incentive for expats working in Antwerp, Ghent, or the Flemish periphery of Brussels.
However, this 3% rate is not a "get out of jail free" card. It comes with very specific strings attached. You must move into the property and register it as your primary legal residence (your domicile) within three years of the purchase. If you fail to do this, the Flemish tax authorities will come knocking for the remaining 9%, plus a hefty fine.
The Energy Efficiency Bonus: The 1 Percent Rate
In an effort to meet European climate goals, Flanders offers an even lower rate of 1% if you commit to a major energy-efficient renovation. Given the current focus on Renovating Properties: EPC Subsidy Applications for Energy Upgrades, this is a popular route for expats buying older Flemish homes. To qualify, you must bring the home's EPC (Energy Performance Certificate) rating up to a specific level within five years.
While the 1% rate sounds like a dream, remember that the cost of labor and materials in Belgium is high. Many expats use profits from their investment portfolios or even assets from Binance to fund these renovations, but be warned: Belgian banks are notoriously skeptical of crypto-sourced funds for home purchases. Always ensure you have a clear paper trail for any capital you intend to use for your real estate project.
Modest Home Reductions in Flanders
If you are buying a relatively "modest" home—typically defined by a purchase price under a certain threshold (around €220,000 to €240,000 depending on the specific commune)—you may even get an additional reduction on the tax base. This means the first slice of your purchase price is essentially tax-free. This makes Flanders particularly attractive for first-time buyers who are still Building Wealth: Investing, Savings Accounts, and Pensions in Belgium and don't have a massive inheritance to fall back on.
Brussels: The 12.5 Percent Reality Check
Brussels takes a very different approach. Instead of a low flat rate, Brussels sticks to a high standard rate of 12.5% but offers a significant "Abattement" or tax-free allowance. For many expats, this is the most confusing part of the Notary Fees and Registration Duties When Buying a Belgian House.
The standard rule in Brussels is that you pay 12.5% on everything. However, if you are a first-time buyer (meaning you don't own another residential property anywhere in the world), you can get an exemption on the first €200,000 of the purchase price. This is a potential saving of €25,000.
Conditions for the Brussels Abattement
To keep this €25,000 "gift" from the Brussels government, the rules are stricter than in Flanders. You must maintain your primary residence in that property for an uninterrupted period of five years. If you get a job offer in London or Singapore and decide to move after three years, you will likely have to pay back the tax savings pro-rata.
Furthermore, the Abattement only applies to properties with a purchase price below a certain ceiling—currently capped at €600,000 in 2026. If your dream apartment in Ixelles costs €600,001, you lose the entire exemption and pay 12.5% on the full amount. This "all or nothing" cliff is why negotiations in Brussels real estate are so fierce around that €600k mark.
Comparing Costs: A Real-World Scenario
Let’s look at a typical €450,000 apartment to see how the numbers actually shake out. This table assumes the buyer qualifies for the primary residence rates in both regions.
| Feature | Flanders (3%) | Brussels (12.5% with Abattement) |
|---|---|---|
| Purchase Price | €450,000 | €450,000 |
| Taxable Base | €450,000 | €250,000 (after €200k Abattement) |
| Registration Duty | €13,500 | €31,250 |
| Notary & Admin Fees | Approx €6,000 | Approx €6,000 |
| Total Cash Needed for Fees | €19,500 | €37,250 |
As you can see, the "cheap" 3% rate in Flanders is still significantly less expensive than the Brussels system, even with the generous tax-free allowance. This is a primary reason why many expat families eventually migrate toward Leuven or Mechelen once they decide to buy.
Navigating the Purchase Process
Regardless of which region you choose, the administrative steps remain similar. Once your offer is accepted, you will sign the What is the 'Compromis de Vente' When Buying Belgian Property?. This is a binding legal document. In Belgium, there is no "gazumping" or backing out without a 10% penalty once this is signed.
The Role of the Notary
In Belgium, the notary represents the state, but you should always hire your own. It costs nothing extra (the two notaries simply split the fixed fee), and having a notary who speaks your language and understands expat concerns is vital. They will handle the calculation of the registration duties and ensure the money reaches the regional treasury.
If you are a non-EU citizen, the notary will also be your guide through the maze of Mortgages (Crédit Hypothécaire) for Non-EU Citizens in Belgium. Some banks may demand a higher down payment if your residence permit is tied to a specific employer, making the upfront tax burden even more of a hurdle.
Moving Money Safely
When it comes time to pay the deposit (usually 10% of the purchase price), it is typically held in an escrow account by the notary or the estate agent. For expats with funds still in their home country, moving these sums requires precision. Using Wise allows you to lock in an exchange rate and ensures the funds arrive in the notary's account exactly when needed. I have seen more than one deal nearly collapse because a traditional bank "flagged" a large international transfer for three days of compliance checks right before the deadline.
Strategic Considerations for Expats
Is it better to buy in Flanders just for the tax break? Not necessarily. You have to balance the €20,000 savings with your lifestyle and commute. If you work in the EU Quarter and don't want to spend two hours a day on the SNCB trains, the Brussels Abattement still offers a decent compromise.
Long-term Planning
If you plan to stay in Belgium for less than five years, the Flanders 3% rate is much more flexible. Because Brussels requires a five-year commitment to keep the tax break, it is a riskier financial move for "nomadic" expats who might be transferred by their company at short notice.
Investment Properties
If you are buying a second property or a buy-to-let investment, the math changes completely. In that case, both Flanders and Brussels charge a flat 12.5%. The "deals" and "carrots" are strictly reserved for people buying their own homes. For those looking to invest without the headache of Belgian property taxes, many expats turn to digital platforms like Trade Republic for stocks or Binance for digital assets, which offer much higher liquidity than a Belgian apartment.
Final Thoughts on Belgian Property Taxes
The gap between 3% and 12.5% is a quirk of Belgian politics that has a massive impact on your bank account. Before you start falling in love with herringbone floors and high ceilings, sit down with a calculator. Ensure you have the "frais" covered in cold, hard cash, and don't forget that the notary's bill will also include VAT on their services and various administrative search costs.
Buying a home here is a marathon of paperwork, but once you get through the registration duty hurdle, you are tapping into one of the most stable (if highly taxed) real estate markets in the world. Just make sure you know which region's treasury you're about to fund.
Disclaimer
This guide is for informational purposes only and does not constitute formal legal, financial, or tax advice. Belgian tax laws, including registration duties and Abattement thresholds, are subject to regional legislative changes and annual indexation. Always consult with a qualified Belgian notary or tax professional before signing a binding purchase agreement or transferring large sums of money.