Buying Property vs Renting in Belgium: Financial 2026 Comparison
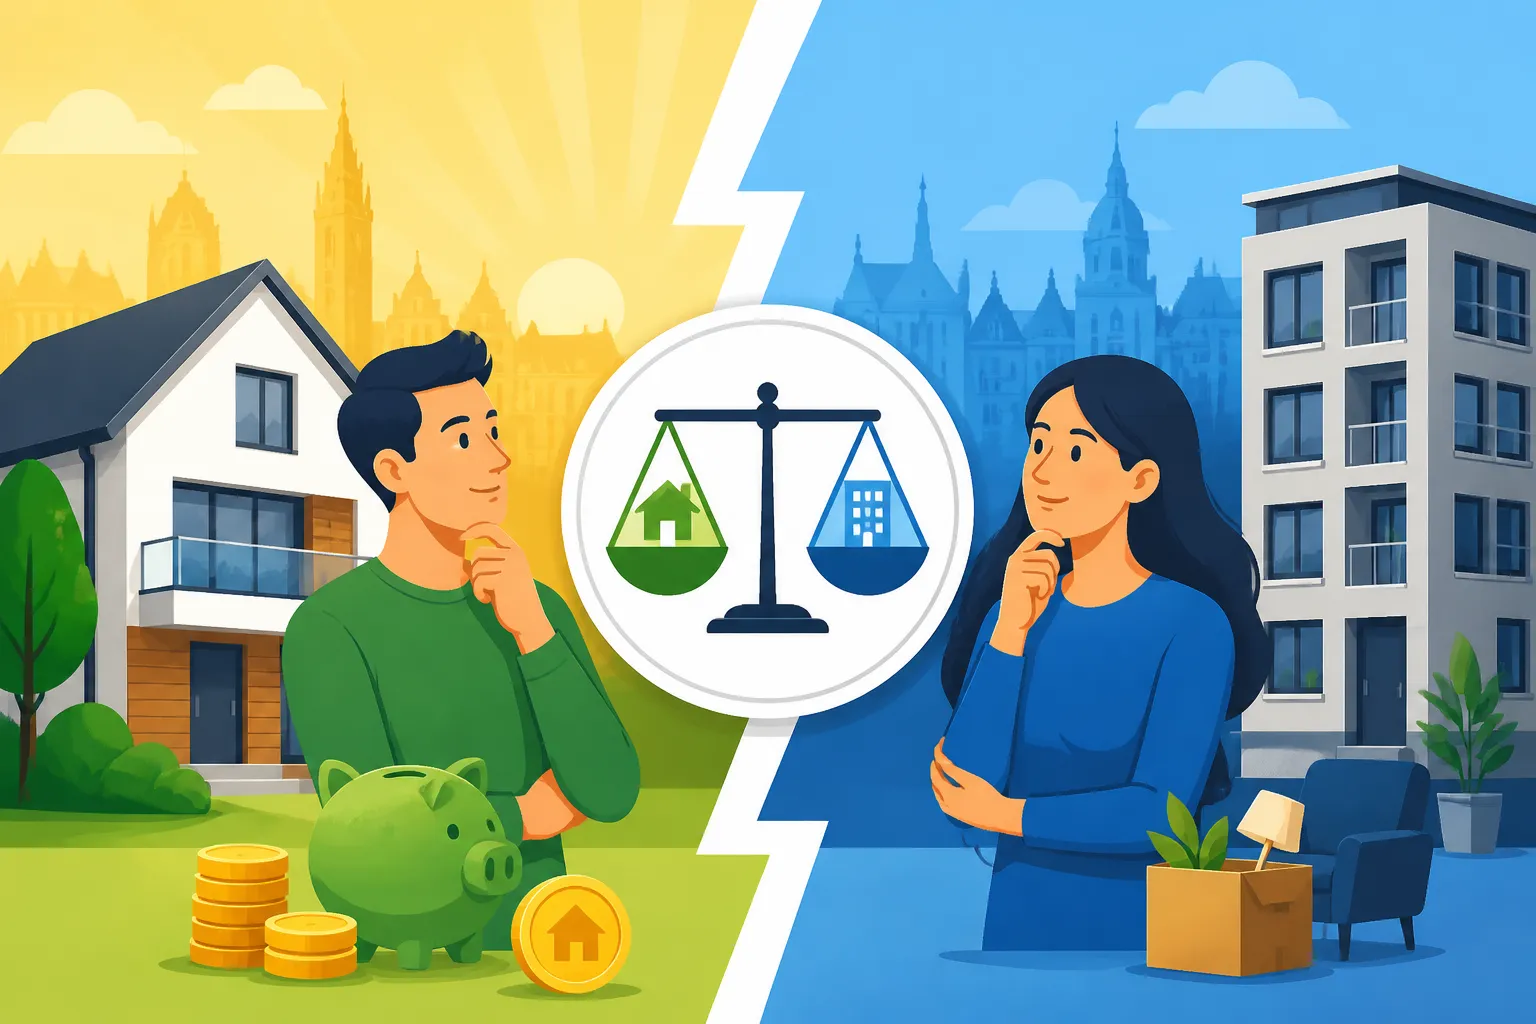
Navigating the Belgian property market often feels like trying to solve a Rubik’s cube while blindfolded, especially when you are hit with high registration taxes or confusing rental indexation. When I first landed in Brussels, I spent months agonizing over whether to commit to a mortgage or keep my flexibility as a tenant. This guide breaks down the financial math of renting versus buying in Belgium, helping you decide which path secures your future without draining your savings.
The Financial Landscape of Renting
Renting in Belgium is often seen as the "safe" entry point for expats, but it is far from a flat-fee experience. The market has shifted significantly over the last few years, with inflation and energy efficiency ratings (EPC/PEB) dictating price points more than ever before. If you are just arriving, you need to understand that the sticker price on Immoweb is only the beginning of your monthly outflow.
The 3-6-9 Lease and Indexation Realities
The backbone of the Belgian rental market is the Understanding the 3-6-9 Lease Contract: The Standard 9-Year Lease. Many foreigners are terrified by the "nine-year" label, thinking they are signing away a decade of their lives. In reality, this structure provides you with significant protection, but it comes with a sting: Indexation of Rent: How Landlords Legally Increase Rent Annually. In 2026, landlords are strictly utilizing the Health Index to adjust your rent every year on the anniversary of your contract.
I remember my second year in Antwerp when my landlord sent a formal letter increasing my rent by nearly 6% due to indexation. It felt like a gut punch, but it was perfectly legal. You must budget for an annual increase of 2% to 5% just to stay in the same apartment. Furthermore, the energy crisis of the previous years has led to a system where landlords of poorly insulated buildings (low EPC ratings) are often restricted from indexing, making Renting in Belgium: Apartments, Contracts, and Tenant Rights (2027) a vital area of study before you sign anything. If you rent a "G" rated apartment in Brussels, you might save on the base rent, but your heating bills will be astronomical, and the landlord's inability to index might lead to deferred maintenance.
Upfront Costs: Deposits and Inventory of Fixtures
Before you even get the keys, you are looking at a massive cash outlay. The standard rental guarantee is usually equivalent to two or three months of base rent. In the old days, we used blocked bank accounts, which were a bureaucratic nightmare to open without a local ID. Today, most expats utilize Rental Deposits in Belgium: e-DEPO vs Blocked Bank Accounts. The e-DEPO system via the FPS Finance portal is much faster, but it still requires you to have your Itsme Authentication: How to Set Up Belgium's Vital Digital ID ready to go.
Beyond the deposit, you must account for the "État des Lieux" (Inventory of Fixtures). In Belgium, this is a professional, legally binding document often prepared by an independent expert. You and the landlord usually split the cost, which can range from 150 to 300 euros each. Do not skip this. I’ve seen expats lose their entire deposit because they didn't document a small scratch on the parquet floor during the move-in. When you consider the Cost of Living in Belgium 2026: Budgeting for Cities and Families, these one-time fees can easily total 5,000 euros for a modest two-bedroom apartment before you've even bought a single IKEA chair.
The Real Cost of Buying in Belgium
Belgium is famously a country with a "brick in the stomach" (brique dans le ventre), meaning almost every local aims to own their home. For an expat, however, the entry costs are some of the highest in Europe. You aren't just paying the property price; you are paying the government a massive "welcome" fee that takes years of price appreciation to recoup.
Notary Fees and Registration Duties
The single biggest barrier to homeownership in Belgium is the registration tax. This varies wildly depending on which of the three regions you are buying in. If you are looking at Registration Duties in Flanders (3%) vs Brussels (12.5%), you will see a massive disparity. Flanders has aggressively lowered its rates for first-time buyers of a primary residence to encourage ownership. Conversely, Brussels remains at 12.5%, though it offers a significant silver lining called the "abattement."
The Brussels Abattement: Tax Discount on Your First Home allows you to exempt the first 200,000 euros (as of 2026) of the purchase price from the 12.5% tax, provided the property is under a certain price cap and you stay there for five years. When I was calculating the numbers for a flat in Ixelles, that abattement saved me 25,000 euros upfront. However, even with the discount, you still need to pay Notary Fees and Registration Duties When Buying a Belgian House, which include the notary's honorarium, administrative costs, and the mortgage registration fee. Generally, you should expect to pay 7% to 15% of the purchase price in "closing costs" that cannot be added to your loan. This means if you buy a 400,000 euro house, you need roughly 40,000 to 60,000 euros in cash just to cover the fees.
Mortgage Requirements and Interest Rates in 2026
Securing Mortgages (Crédit Hypothécaire) for Non-EU Citizens in Belgium has become more streamlined but remains strict. Most Belgian banks—like KBC, BNP Paribas Fortis, or ING—require a 10% down payment on the property price, plus the ability to pay the closing costs in cash. If you are a non-EU citizen, they might ask for a 20% down payment unless you have a "Single Permit" with a long-term outlook.
Interest rates in 2026 have stabilized, but they are no longer at the historic lows of the previous decade. Banks will scrutinize your "capacity to repay," ensuring that your total debt (including the new mortgage) does not exceed 33% to 40% of your net monthly income. If you are moving large sums of money from abroad for your down payment, using a service like Wise is often the most cost-effective way to handle the currency exchange, as Belgian banks tend to charge high spreads on non-EUR transfers. I once saved nearly 800 euros on a transfer from the UK just by avoiding the traditional bank's exchange rate.
Financial Comparison Table: Renting vs. Buying (2026 Forecast)
| Expense Category | Renting (Monthly/One-time) | Buying (Monthly/One-time) |
|---|---|---|
| Upfront Cash | 2-3 months rent + expert fees | 10-20% down payment + 7-15% tax/fees |
| Monthly Payment | Base Rent + Charges (Fixed-ish) | Mortgage Principal + Interest |
| Maintenance | Minor repairs only | Full responsibility + Boiler checks |
| Taxes | None (Usually included in rent) | Property Tax (Précompte Immobilier) |
| Flexibility | High (3-month notice) | Low (Costly to sell before 5 years) |
| Equity Building | Zero | 100% of principal paid |
| Wealth Opportunity | Keep cash in Trade Republic / Stocks | Capital locked in the walls |
Investment Comparison: Real Estate vs. Liquid Assets
One of the biggest mistakes expats make is assuming that because they "can" afford a mortgage, they "should" buy. In Belgium, the high transaction costs mean your property has to appreciate by at least 10% to 15% just for you to break even. If you plan to leave Belgium in three years, renting and investing your surplus cash is almost always the better financial move.
Maintenance and the Property Tax Burden
When you own a home in Belgium, you are responsible for the "Précompte Immobilier." This is an annual property tax based on the "Cadastral Income" of the house. It’s essentially a "rent" you pay to the state for the privilege of owning. For a standard house in a suburb like Tervuren or Waterloo, this can be anywhere from 800 to 2,500 euros per year.
Then there is the maintenance. Belgian houses are often old and prone to humidity. As a renter, a leaking roof is your landlord's financial nightmare. As an owner, it's yours. In my experience, you should set aside 1% of the property's value every year for maintenance. If you don't, you'll find yourself struggling when the 20-year-old boiler finally gives up during a snowy February.
Opportunity Cost and Alternative Investments
If you choose to rent, you have a massive lump sum of cash (that 60,000+ euros for the down payment and fees) that can be working for you elsewhere. For instance, putting that money into a high-yield cash account or an ETF via Trade Republic can yield a steady 3% to 4% return with total liquidity. For the more risk-tolerant expat, keeping a portion of your portfolio in digital assets via Binance offers a different growth trajectory that isn't tied to the Belgian housing market's slow and steady 2-3% annual growth.
When you factor in the "opportunity cost," buying a house starts to look less like a guaranteed win and more like a lifestyle choice. If your 60,000 euros earns 4% annually in a diversified portfolio, that’s 2,400 euros a year in passive income. To match that, your Belgian house needs to appreciate significantly while you also pay for repairs, taxes, and mortgage interest.
Regional Nuances: Where the Math Changes
The decision to buy or rent changes the moment you cross a regional border. Belgium is a patchwork of tax laws, and where you work doesn't always have to be where you live.
The Brussels Factor and the Five-Year Rule
In Brussels, the 12.5% registration tax is a massive hurdle. However, the region is also the most dynamic rental market. If you are an EU official or a consultant, renting in Ixelles or Etterbeek gives you the ability to walk to work and move when your contract ends. Buying in Brussels only makes sense if you are 100% certain you will stay for at least five to seven years. This is because of the "restitution" rules; if you sell too quickly, you may not be able to carry over any tax benefits, and the high selling costs will eat your equity.
Secondary Cities: Antwerp, Ghent, and Mechelen
Flanders has made it much more attractive to buy. With a 3% registration tax, the "break-even" point for buying versus renting is much shorter—often around three to four years. In cities like Ghent or Mechelen, the demand for housing is sky-high, and the rental market is extremely tight. I have friends in Ghent who chose to buy a small townhouse because the monthly mortgage was actually lower than the rent for a similar-sized apartment, and the 3% tax meant they only needed about 20,000 euros in cash to close the deal.
Practical Scenarios: Renting vs. Buying Decision Matrix
To simplify your choice, I've created a mental checklist based on the conversations I’ve had with dozens of expats over the years.
- Scenario A: The Short-Term Project (1-3 Years). You are here on a fixed-term contract. Decision: Rent. The registration taxes in Belgium will swallow any potential gains. Keep your deposit in a secure Wise account or a liquid savings platform.
- Scenario B: The "I Love Belgium" Expat (5+ Years). You have a permanent contract (CDI) and see yourself staying in the same city. Decision: Buy. Especially in Flanders, the equity you build over five years will far outweigh the rental payments and the 3% tax. In Brussels, ensure you qualify for the abattement.
- Scenario C: The Remote Worker / Digital Nomad. You want to explore different vibes—from the coast to the Ardennes. Decision: Rent. Use the flexibility to test neighborhoods. You can manage your finances entirely through neo-banks and investment apps while staying mobile.
Ultimately, the choice between buying and renting in Belgium in 2026 isn't just about the monthly payment. It is about your "exit strategy." Belgium is a country that rewards those who stay put and punishes those who move frequently with high transaction taxes. If you are ready to settle, the "brick in the stomach" will serve you well. If you are still exploring, let the landlord handle the leaks while you build your wealth in more liquid markets.
Disclaimer
This guide is for informational purposes only and does not constitute professional financial, legal, or real estate advice. Belgian tax laws and regional regulations are subject to frequent changes, and the 2026 data mentioned reflects current trends and projections. Always consult with a certified notary, tax advisor, or mortgage broker before making significant financial commitments in Belgium. Transactions in real estate and financial markets involve risks, and past performance of property appreciation or investment returns is not a guarantee of future results.